A tax-smart suite: What "tax efficiency at scale" actually requires
Rules-based tax tools integrate with your custodian and each other, automating tax-loss harvesting, asset location, and rebalancing across the full bookPublished November 19, 2026 • 9 min read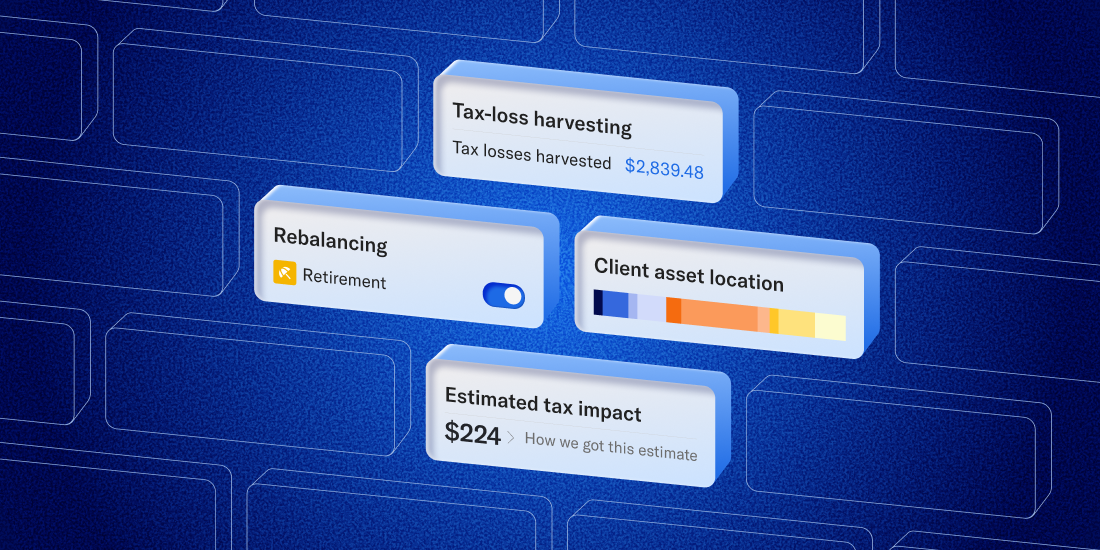
Kelly ChambersFinancial writer
Key takeaways
- At many firms, manual tax planning happens in the last six weeks of the year. This increases year-end workload and leaves harvesting opportunities from the other ten months unused.
- Tax drag can reduce portfolio returns by an estimated 1% to 2% annually. Tax-loss harvesting alone can add an estimated 0.47% to 1.27% in annual after-tax return.
- Manual tax management rarely gets past an advisor's top relationships. The administrative work grows with every account, making it nearly impossible to give the same treatment to all clients.
- But tax planning doesn’t have to be manual: Automated, rules-based tools apply the same tax strategy to every enrolled account, all year. The advisor still sets the gains allowance, drift thresholds, and migration strategy.
- Betterment Advisor Solutions builds tax management into the custodial platform, so the work can run across every enrolled account. Learn more.
Does your firm provide the same level of tax planning year-round for its whole book of business?
For many practices, the honest answer is no.
Picture a typical 200-client book: Manual tax strategy gets run well, by hand, for the top 20 relationships. The other 180 or so get an annual review and whatever still fits in the last weeks of Q4.
That gap isn't a question of diligence; it’s more about the system you’re running. Without a comprehensive tax planning system in place, the December 31 deadline creates a predictable pileup of manual work.
But what if you could increase your firm’s efficiency and create more value for your clients throughout the year? A custodian that offers tax-smart tools can help you maximize clients' after-tax returns, all year, for any account, without adding to your plate.
What does "tax efficiency at scale" actually require?
Tax efficiency across a full book requires running multiple jobs together, instead of as separate manual chores. You can control how these jobs work, but you don’t have to “press enter” every time you want them to run.
With Betterment Advisor Solutions, automation can do the work for you:
- Tax-smart transitions: You control the timeline, but automation takes care of unwinding concentrated stock, inherited portfolios, and outdated allocations. You set the capital gains allowance, choose one of three tax-aware migration strategies, and move the assets. Tax-loss harvesting works the position alongside the transition, freeing up allowance to move more of it each year.
- Tax-smart ongoing management: Your firm can leverage a suite of optional, custom, rules-based features for integrated management across your book. Tax-loss harvesting scans for opportunities year-round. Asset location coordinates asset placement across eligible account types to improve after-tax outcomes. Drift-based rebalancing holds the portfolio to the thresholds you set, and you can switch it off.
- Tax-smart withdrawals: Your clients benefit as every sale runs through a tax-minimization algorithm, and you can override it, picking the selling strategy that matches the client's situation rather than accepting a default. You see a tax impact preview before the trade goes out, helping prevent surprises for you or for your client.
Any one of these is manageable by hand for a handful of clients, but you have to be able to manage them together for clients as your firm grows. Run separately, or only for some clients, they could leave after-tax returns on the table, but when automated and integrated, they help your clients every day of the year.
Manual tax planning doesn't scale
When a client arrives with appreciated or legacy holdings, advisors have traditionally had two options:
- Park the legacy positions in a separate account
- Hand-build a custom portfolio around them
The first leaves a fragmented portfolio that may not match the client's actual risk tolerance. The second works, but only with constant hands-on monitoring.
In our Tax-smart transitions whitepaper, we outline three costs of running transitions this way:
- High administrative burden
- Limited tax efficiency without a systematic rules-based approach
- Suboptimal portfolio alignment as transitions get delayed
With hundreds of clients, manual planning costs time and money for you and your clients.
Beyond transitions, tax-loss harvesting has similar constraints. Manually approving batches of trades needs continuous monitoring and execution. That's difficult across dozens of clients and effectively impossible across hundreds. Hiring more staff mostly just moves the bottleneck and increases cost.
What changes when tax management is automated throughout your firm?
Tax strategy stops being a per-client project and becomes a firm-wide procedure: The same rules run on every account, every day. Turning it on for one client or for hundreds is the flip of a toggle with the right digital tax management platform.
With Betterment, automated tax management offers you a handful of features to leverage across your clients.
Feature | What it does | Why it matters for your practice |
|---|---|---|
Automated tax-loss harvesting | The TLH algorithm scans accounts regularly for opportunities to sell a security at a loss, then replaces it with a similar security (a secondary or IRA secondary ticker within the same security group) to help avoid wash sales while keeping the client in roughly the same allocation. | Realized losses can lower a client's tax bill by offsetting gains (and, within limits, income) elsewhere in their return. That offset can happen throughout the year, on every enrolled client. |
Optimized tax-lot selection | A tax-minimization algorithm selects the most tax-efficient lots for every sale, prioritizing losses and then long-term gains, and applies automatically to any sale on the platform. | Routine rebalancing, withdrawals, and transitions use tax-aware lots by default. You don't make a tax-lot decision on every trade. |
Customizable drift-based rebalancing | Automated rebalancing runs by default on every portfolio, keeping it aligned with its target allocation. You can set a custom drift threshold per client, or turn automated rebalancing off for a specific client you'd rather manage manually. | Keeping drift low protects the risk/return profile each client is set up for, without having to monitor every account. |
Automated asset location | The least tax-efficient assets are placed in tax-advantaged accounts (traditional and Roth IRAs, 401(k)s), while the most tax-efficient assets go in the taxable account, coordinated automatically across accounts. | Helps clients improve after-tax returns by matching specific investments with the account type. Placement runs across accounts instead of account by account. |
Tax-aware portfolio transitions | Whenever you transition a portfolio onto the platform or change a client's target portfolio strategy/allocation, you choose one of three tax-aware migration strategies, and can layer an annual gains allowance on top to cap what gets realized. | Traditionally, moving a client to a new strategy can trigger a larger tax bill in a single year. You control how much gets realized and how fast. |
Sell-order flexibility | Choose which selling strategy is applied when exiting a specific position. | Match the exit approach to each client's situation, position by position. |
Feature | What it does |
|---|---|
Automated tax-loss harvesting | The TLH algorithm scans accounts regularly for opportunities to sell a security at a loss, then replaces it with a similar security (a secondary or IRA secondary ticker within the same security group) to help avoid wash sales while keeping the client in roughly the same allocation. |
Optimized tax-lot selection | A tax-minimization algorithm selects the most tax-efficient lots for every sale, prioritizing losses and then long-term gains, and applies automatically to any sale on the platform. |
Customizable drift-based rebalancing | Automated rebalancing runs by default on every portfolio, keeping it aligned with its target allocation. You can set a custom drift threshold per client, or turn automated rebalancing off for a specific client you'd rather manage manually. |
Automated asset location | The least tax-efficient assets are placed in tax-advantaged accounts (traditional and Roth IRAs, 401(k)s), while the most tax-efficient assets go in the taxable account, coordinated automatically across accounts. |
Tax-aware portfolio transitions | Whenever you transition a portfolio onto the platform or change a client's target portfolio strategy/allocation, you choose one of three tax-aware migration strategies, and can layer an annual gains allowance on top to cap what gets realized. |
Sell-order flexibility | Choose which selling strategy is applied when exiting a specific position. |
Why it matters for your practice |
|---|
Realized losses can lower a client's tax bill by offsetting gains (and, within limits, income) elsewhere in their return. That offset can happen throughout the year, on every enrolled client. |
Routine rebalancing, withdrawals, and transitions use tax-aware lots by default. You don't make a tax-lot decision on every trade. |
Keeping drift low protects the risk/return profile each client is set up for, without having to monitor every account. |
Helps clients improve after-tax returns by matching specific investments with the account type. Placement runs across accounts instead of account by account. |
Traditionally, moving a client to a new strategy can trigger a larger tax bill in a single year. You control how much gets realized and how fast. |
Match the exit approach to each client's situation, position by position. |
Did you know? Tax automation can pay for itself. 66% of customers using our tax-loss harvesting features had their Betterment fee covered by likely tax savings. Learn more. Proximate disclosure: Based on 2022-2025 retail taxable accounts with TLH enabled for at least 1 yr. Tax savings use self-reported income, filing status, and dependents, and exclude transactions at other brokerages. Applies 2025 tax rates to all harvested losses (long-term/short-term rates as applicable), assuming full use against taxable gains. Not performance; not guaranteed. Disclosures at Betterment.com/details. [LINK: https://www.betterment.com/details] |
|---|
Did you know? Tax automation can pay for itself. 66% of customers using our tax-loss harvesting features had their Betterment fee covered by likely tax savings. Learn more. Proximate disclosure: Based on 2022-2025 retail taxable accounts with TLH enabled for at least 1 yr. Tax savings use self-reported income, filing status, and dependents, and exclude transactions at other brokerages. Applies 2025 tax rates to all harvested losses (long-term/short-term rates as applicable), assuming full use against taxable gains. Not performance; not guaranteed. Disclosures at Betterment.com/details. [LINK: https://www.betterment.com/details] |
|---|
What about clients you can’t transition? Every firm has them. Clients whose gains made a portfolio change unwise. Scenarios like concentrated employer stock, inherited portfolios, or allocations shaped by a risk profile from a decade ago.
A full liquidation would mean an outsized tax bill, so they sit in the "some other day" pile.
But a gains allowance turns "some other day" into a schedule.
Custom gains allowances are in place to control total capital gains realized in a year, from transition to withdrawal.
In an illustrative scenario, with a $25,000 annual gains budget, it would take approximately 4 years to complete the transition, whereas with a $10,000 gains budget, the transition would stretch out to about 10 years.
And if you use Betterment’s gains allowance feature along with automated tax-loss harvesting, it can reduce your client’s capital gains burden. This process creates tax losses that can be used to neutralize gains, essentially freeing up more gains allowance and increasing the amount of stock that can be transitioned without incurring additional taxes. The client sees a schedule they agreed to, not a surprise bill.
Why Betterment Advisor Solutions for tax optimization
With Betterment Advisor Solutions, tax optimization tools sit inside the custodial platform, all under one platform fee.
- There's no separate overlay to buy, integrate, or reconcile. Harvesting, lot selection, asset location, drift-based rebalancing, and tax-aware transitions. They all run as one system with you in control.
- Plus, Betterment’s tax-smart tools have been refined for more than a decade.
Want to learn more? Explore our tax management solutions.
FAQ
Q: What is automated tax-loss harvesting?
Automated tax-loss harvesting is software that regularly scans client accounts for securities that can be sold at a loss, then replaces each sold security with a similar one to help avoid wash sales and keep the target allocation. The realized losses can offset capital gains and, within IRS limits, ordinary income. This runs throughout the year, not only at a year-end review.
Q: How can advisors transition client portfolios, or move clients into a new portfolio, without triggering a large tax bill?
Tax-aware migration strategies let advisors control how a transition happens: gradually through cash flows to reduce short-term gains and wash sales, by setting the target only, or through an immediate rebalance without tax constraints. An annual gains allowance caps how much gain is realized each year, so the tax cost can be spread over a timeline the client can plan around.
Q: What is a capital gains allowance?
A capital gains allowance is an annual ceiling an advisor sets on realized capital gains, at the household or individual taxpayer level. Once net realized gains reach the allowance, Betterment's proactive rebalancing will only sell assets at a loss until gains fall back below the ceiling.
Q: What is asset location, and why does it matter?
Asset location places the least tax-efficient assets in tax-advantaged accounts (like IRAs and 401(k)s) and the most tax-efficient assets in taxable accounts. It can improve what clients keep without changing what they're invested in, only where each asset is held. Betterment automates this coordination across a client's accounts.
Q: Does automated tax management mean giving up control of client portfolios?
No. You still set the policy: gains allowances, drift thresholds, migration strategies, and sell-order preferences. The system carries them out. What you stop doing is the monitoring and trading by hand.
Kelly ChambersFinancial writer
Kelly Chambers is a finance writer with two decades of leadership experience in the financial services industry. Along with Betterment, his work has included collaborations with leading financial brands such as Goldman Sachs, BlackRock, and Prudential.