All the features you want, none of the headache.
Your clients deserve a solo that’s flexible, full-scale, and effortless to manage—from account opening to funding, conversions, and ongoing management.
Webinar: Raising the bar on solo 401(k)s for you & your clients
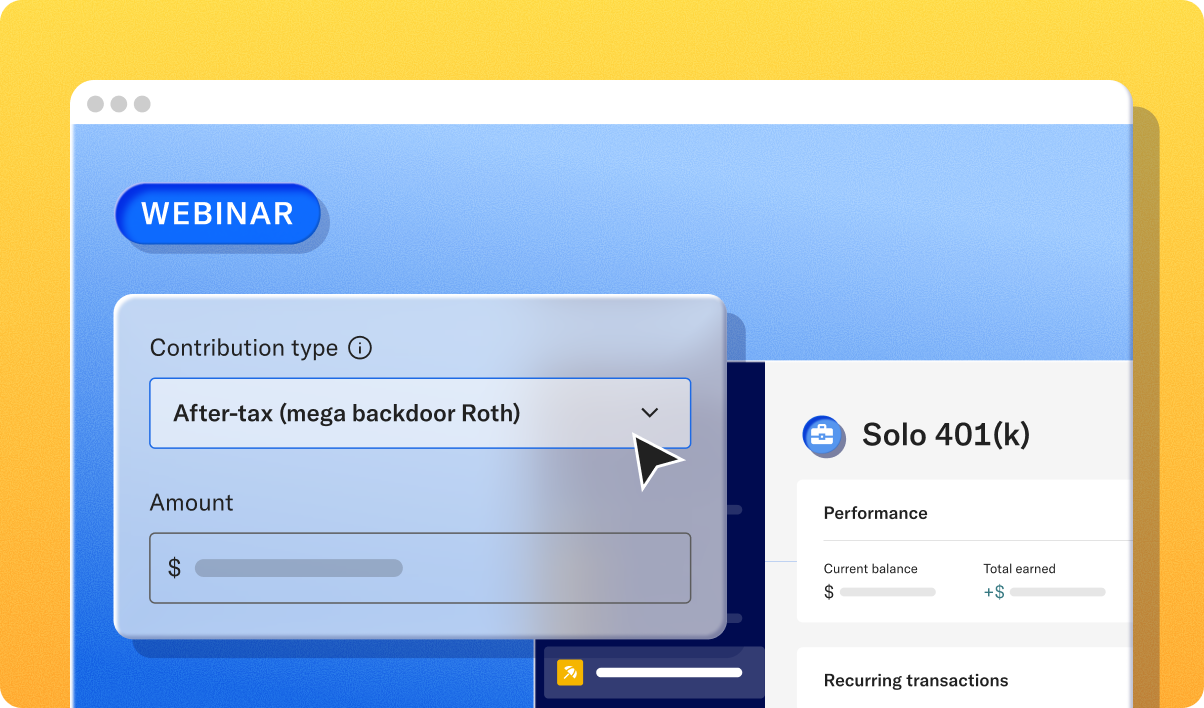
Webinar Live: Mega backdoor Roth in the solo 401(k)
Join us for a closer look at the strategy, the client profile, and the streamlined Betterment experience.
November 5, 1:00 PM ET
Retirement solutions for all.
Betterment should easily be the first choice for solo 401(k)s.
FAQs
Solo 401(k) eligibility is limited to self-employed individuals or business owners without employees. There are no age or income restrictions.
“Owners” must have at least 5% ownership share and have some self-employed income. “Employees” are defined as individuals earning an income from the business, who are at least 21 years old, and have worked over 500 hours per year for 3 consecutive years. The only exception to the employee rule is a spouse.
Spouses can participate in a solo 401(k) plan if they are a full-time employee or an owner earning income from the business. Spouses each have their own individual contribution limits, doubling the total amount a household is eligible to save annually.
In 2026, the total individual contribution limit is $72,000, or 100% of compensation if that’s less. Clients can contribute as both the employee and the employer.
As the employee, the client can defer up to $24,500, or 100% of compensation, whichever is less. As the employer, they can add a profit-sharing contribution of up to 25% of compensation or net self-employment income (see nuances by business entity here).
After-tax contributions also count toward the $72,000 IRS limit. Read more about mega backdoor Roth below.
Those ages 50–59 and 64+ can contribute up to an additional $8,000 in catch-up employee contributions ($32,500 total). Under the SECURE 2.0 Act, those ages 60–63 can use a higher catch-up limit of $11,250. Catch-up contributions don’t count toward the $72,000 limit and can’t be made as after-tax contributions.
Yes! Employee contributions can be either pre-tax or Roth.
Employee contribution limits are up to $24,500–$35,750 in 2026 (depending on age and total income), or more than 3x the Roth IRA limit.
Eligible clients can also move more money into their Roth Solo 401(k) through a mega backdoor Roth.
SECURE Act 2.0 has several provisions that impact solo 401(k) contributions, including retroactive salary deferrals. This provision now allows eligible employers to establish and fund a solo 401(k) plan with salary deferrals for the prior tax year.
This means that clients who start new solo 401(k) plans in 2026 can make tax-deductible contributions for the 2026 tax year up until October 15, 2026, or their tax filing deadline.*
The solo 401(k) setup process is simple, accessible, and fast. To fund, your clients can simply link their business bank account and set up contributions via the client portal. You can also convert an existing solo 401(k) plan to a Betterment solo 401(k) via the standard account opening flow in the advisor dashboard.
Clients may be eligible to rollover the following accounts into a traditional solo 401(k): Qualified plans (pre-tax), traditional IRA, SIMPLE IRA (after two years), SEP-IRA, Governmental 457(b), and pre-tax 403(b). Clients may be eligible to rollover the following accounts into a Roth solo 401(k): Designated Roth accounts, qualified plan (pre-tax), Governmental 457(b), pre-tax 403(b). For more information, see here.
Note: All 401(k) to 401(k) rollovers must be initiated by the client in the client portal.
A mega backdoor Roth lets clients make after-tax contributions to their Traditional Solo 401(k) and convert them to their Roth Solo 401(k) through an in-plan conversion. It’s available on every Betterment solo 401(k), including existing plans, with no extra setup. After-tax contributions count toward the $72,000 annual limit (2026).
A mega backdoor Roth is a complex strategy not right for everyone. Learn more.
We provide comprehensive customer support to help you and your clients feel at ease. From onboarding and account transfers to ongoing platform guidance and day-to-day troubleshooting, our dedicated teams are reachable.
Our advisor servicing team takes a minute to answer your call on average.* Beyond reactive support, we offer on-demand training, webinars, and personalized training sessions to help you maximize the platform. Whether you’re navigating complex client needs or exploring new features, we’re here to help you grow better.
Based on Betterment internal data October 2025 - March 2026.